Borrowing 101: Easy Money Guides
A co-signer is someone who agrees to be responsible for another person’s debt. Co-signing an agreement may help a person qualify for a loan, but it may expose them to a lot of problems, including being responsible for payments, being contacted for payments, bad credit, and eventually an even bigger burden. The best way to[…]
A credit builder loan is a form of small installment loan that is designed to build credit. In this case, the lender doesn’t give the borrower the proceeds of the loan up front. Instead, the lender will place the loan amount in a locked account. The borrower then makes scheduled payments, and the lender releases[…]
The debt snowball method encourages people to pay off their smallest debts first. While continuing to pay the minimum on all other debts, people are instructed to pay as much of the excess payment as possible on the smallest debt. When the smallest debt is completely paid off, the same payment amount that was previously[…]
Just because there’s no traditional credit check for certain loans doesn’t mean there’s no underwriting. Lenders still need a basis for deciding whether to extend credit and on what terms. The review may incorporate application data, bank account cash flow data, proof of income, current debt data, identity verification, a soft credit check, a combination[…]
Direct lenders and loan matching services each have their own responsibilities toward borrowers. A direct lender makes the loan and is named as the creditor in the loan documentation. A loan matching service collects information about a potential borrower to try to match that borrower with a lending or service provider. The matching service does[…]
A credit repair process is not going to completely eliminate information from your credit report that is accurate, nor will it assure a certain credit score. It is entirely made up of two components: the first is correcting incorrect information, and the second is developing positive information over time. It is important to understand the[…]
When used as a term, Cash Advance describes many different ways to get money before you have it. This can include Payday Loans, cash withdrawals made against a credit card, or the advance of wages earned but not received. Because each of these describes a different method of getting money, there are varying costs associated[…]
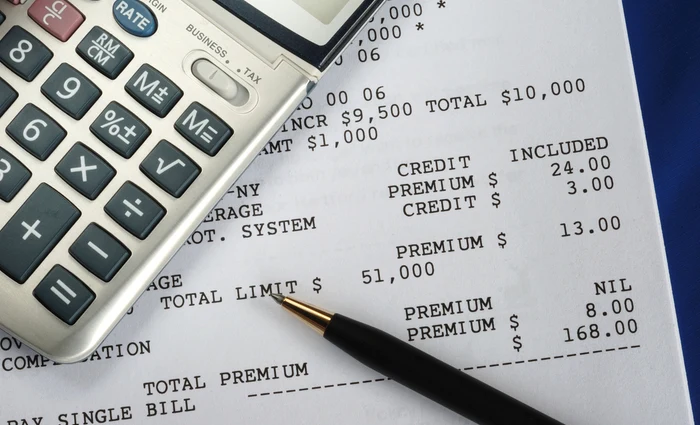
When you take a loan, there are expenses beyond the principal. The highest cost usually comes from interest. Pay attention to lender fees and the payment schedule, too, as they will alter your total cost of credit. When comparing loans, consider the dollar finance charge, APR, payment schedule, and total of payments, not just the[…]
Credit reports are a big part of loan applications, but they aren’t the only part. Bank statements and data on your account transactions can be used to check your income, check and analyze your cash flow, check if you own your account, and see if you can afford the monthly payments. Because there is no[…]
A low credit score can be difficult to understand, let alone explain. It alone cannot predict a lender’s decision, suggest why your credit score is low, or indicate whether you can afford a new payment. A 450 credit score can make it difficult to qualify for a traditional loan. You may also end up with[…]